INDEPENDENT BUSINESS VALUATION SPECIALISTS
XVALUNITED
KINGDOM
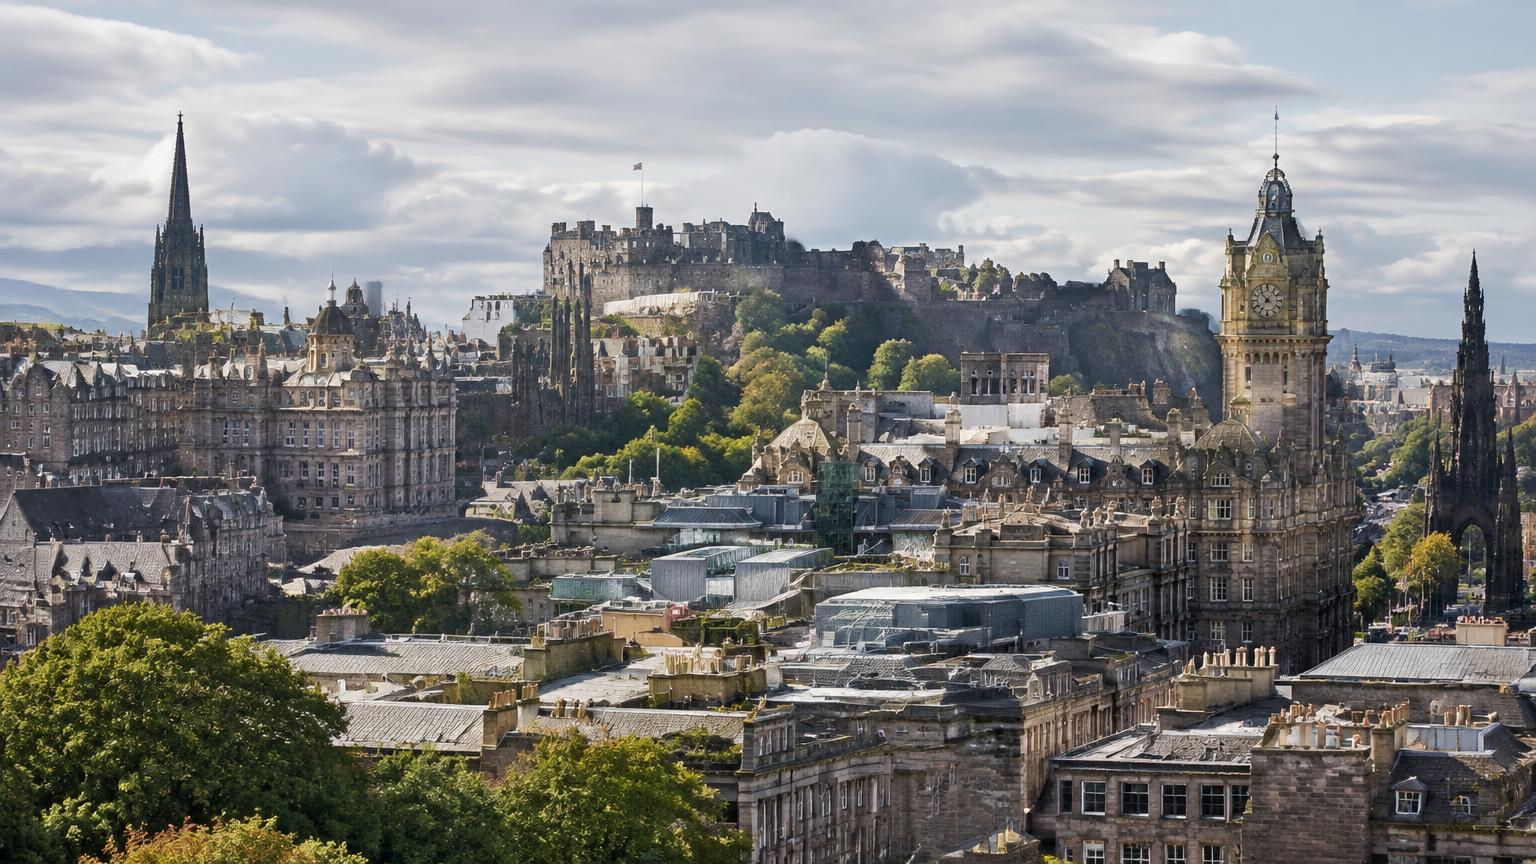
Edinburgh regional architecture

Where we work · Scotland

Business valuation in Edinburgh.
The context behind the value.

Edinburgh & Scotland. Independent analysis for owners and advisers, with the purpose, share rights and jurisdiction clearly defined before work begins.

Independent judgementSame-day enquiry reviewStrictly confidential

Scotland

Jurisdiction confirmed at instruction

Business & shares

Company value and actual ownership rights

Expert-led

Commercial evidence, not regional averages

A confidential conversation

An important decision deserves an independent view.

Tell us about your company, your objectives and your timeframe. We will review the instruction before proposing a scope, fee and delivery timetable.

  • Independent opinion, never an automated estimate
  • Scope, fee and timetable agreed before work begins
  • Confidential from the outset

Prefer to call? +44 20 3996 6807

Prefer WhatsApp? Message us on WhatsApp

What happens next

  1. 1.We review your enquiry the same working day
  2. 2.A short call to understand your circumstances
  3. 3.A written scope, fee and timetable is proposed

No obligation. No automated valuation. No documents required.

In brief

Business valuation in Edinburgh: what we do.

Areas covered: Edinburgh, the Lothians, Fife and the Scottish Borders.

XVAL provides independent business and share valuations in Edinburgh and the Lothians, prepared under Scots law where the instruction requires it. Edinburgh’s financial services, fund management, technology and professional firms often need valuations for fundraising, share schemes, partner exits and family-law matters, where the “relevant date” under Scottish family law is decisive.

Key sectors in Edinburgh & Scotland

Sector drivers we examine in Edinburgh.

01

Financial services and asset management

Assets under management, fee rates, regulatory capital and client retention.

02

Fintech and software

Recurring revenue, development capitalisation and funding runway.

03

Professional partnerships

Partner capital, goodwill and the terms of the partnership agreement.

04

Hospitality and tourism

Seasonality, property and the sustainability of post-festival trading.

The local business context

Understanding the business
behind the balance sheet.

Edinburgh’s business community includes financial services, professional practices, technology and life sciences. Scotland’s wider SME base also includes tourism, energy supply chains and specialist manufacturing.

Our instruction focuses on the individual company. The resilience of revenue, quality of earnings, dependence on key people and rights attached to the holding are examined directly. A regional growth story is not evidence that every business benefits equally.
What matters in the valuation

The issues that deserve
closer examination.

Regulated businesses and professional firms may require particular attention to permissions, client relationships and key personnel. Growth companies need careful treatment of development expenditure, funding requirements and investor rights.

Earnings quality

Reported profit is reconciled to sustainable performance, with evidenced adjustments rather than unsupported add-backs.

Cash conversion

Tax, maintenance investment and working capital determine the cash that remains after operating profit.

Ownership rights

Control, preferences, restrictions and transfer provisions shape the value of the actual holding.

Comparable evidence

Sector and transaction evidence is assessed for scale, timing, risk and economic terms.

Ownership change

Succession, transactions
and the next chapter.

UK tax valuation principles may apply, but Scottish succession, family law and court procedure differ from England and Wales. We confirm the jurisdiction and adviser’s instruction instead of reusing an English litigation scope.

Value is not the same as affordability.

The next owner’s ability to fund a purchase does not, on its own, establish market value. We distinguish a defensible share valuation from the cash-flow capacity supporting debt service, vendor loans or deferred payments.

Legal documents, tax consequences and eligibility for reliefs are addressed by the appointed advisers. The valuation supplies an evidence base; it is not a transaction guarantee or a tax-planning recommendation.

Typical instructions in Edinburgh

Situations we are asked to value.

Financial provision on divorce

Valuing a shareholding at the relevant date, usually separation, under the Family Law (Scotland) Act 1985.

Fintech fundraising

Supporting a pre-money valuation and the pricing of employee options.

Partner retirement

Valuing a partner’s interest under the partnership agreement and partnership law.

Legal framework · Scotland

Scots law changes the valuation question.

Scotland has its own courts, family law and succession rules. Company law and UK taxes largely apply across Great Britain, but the instruction must be framed under the correct procedure from the outset.

Shareholder disputes

An unfair prejudice petition under s.994 Companies Act 2006 is brought in the Court of Session or the sheriff court. The share basis, valuation date and any minority discount follow the remedy sought.

Divorce and separation

Under the Family Law (Scotland) Act 1985, matrimonial property is generally valued at the “relevant date”, usually the date of separation, rather than the date of the hearing.

Estates and succession

Inheritance Tax is UK-wide, so IHTA 1984 s.160 market value applies, but legal rights of a surviving spouse or children under Scottish succession law can affect how the estate and shares are dealt with.

Transactions

Land and Buildings Transaction Tax replaces SDLT for Scottish property, relevant where trading premises sit inside the company being valued.

Local questions

A clear starting point.

Generally yes. Matrimonial property is valued at the relevant date, usually separation, not at the date of proof.

Professional references

IVSC — International Valuation StandardsHMRC — Shares and Assets Valuation Manual

General technical information. Scope, competence, conflicts and jurisdiction are checked before acceptance. No physical office or local market statistics are asserted.

Our wider coverage

XVAL service areas across the UK and IrelandCity markers link to local valuation pages. Ireland is a separate jurisdiction. Locations indicate service areas, not offices.LondonManchesterBirminghamEdinburghBelfastDublin · IrelandLeedsLiverpoolBristolCambridgeOxfordNewcastleCardiffGlasgow
Service areas, not office locations. Republic of Ireland assignments are scoped separately. Geography: Natural Earth (public domain).
Explore all service areas